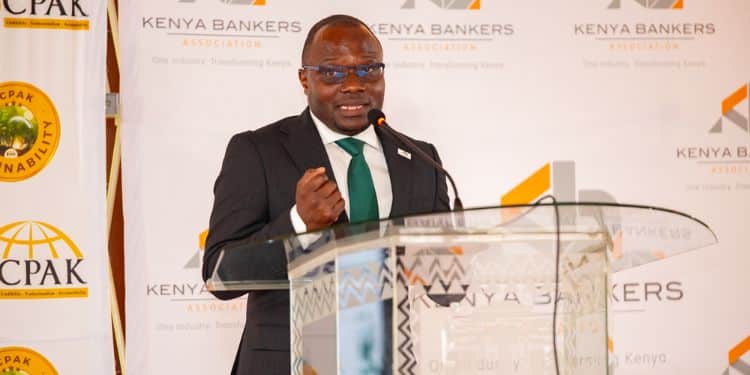
The Kenya Bankers Association (KBA) has warned that proposed capital and liquidity requirements could slow lending to customers, particularly small businesses, as banks work to meet the Ksh10 billion minimum core capital requirement.
Addressing the media on September 24, Raimond Molenje, KBA Chief Executive Officer said increasing capital and liquidity requirements for Tier One banks could force them to slow down lending to customers.
He said the proposal should wait until all banks have first met the Ksh10 billion minimum core capital requirement.
“Now, when you come in and also ask the Tier One banks to be able to increase their (1:48) capital and increase their liquidity ratios, what that means is even the Tier One banks will also put some brake on lending to customers.
So, good proposal, but wrong timing. It needs to wait. We need first to fix the 10 billion core capital for every bank in Kenya,” Raimond Molenje said.
The association argued that the new rules should be implemented after banks have completed the transition to the KSh10 billion core capital requirement.
KBA Says CBK Proposed Rules Could Make It Harder for Kenyans to Get Loans
On the other hand, the Central Bank of Kenya (CBK) has defended the proposed changes, saying it continues to engage banks and other industry players as it reviews policies and regulations governing the sector.
CBK Deputy Governor Gerald Nyaoma said the regulator’s approach aims to strengthen the banking sector while promoting competition and resilience.
He noted that industry input had contributed to several major banking reforms introduced over the past two years.
”The Central Bank of Kenya (CBK) remains committed to working with the industry players in bringing the desired changes in policies and regulations, with the ambition of creating a competitive, resilient and well-functioning banking sector,” he said.
Also Read: How Landlords and Employed Kenyans Drive Most Bank Defaults — CBK
What Does the Proposed Rule Say
The proposed CBK framework focuses on domestic systemically important banks (D-SIBs), which are large or highly connected lenders whose financial difficulties could have wider consequences for Kenya’s banking system and economy.
Under the draft rules, CBK could limit a D-SIB’s expansion or introduction of new products where such activities are considered likely to increase risks to the financial system.
The framework would also require systemically important banks to maintain additional Common Equity Tier 1 (CET1) capital.
Also Read: CBK Approves Major Transfer of Access Bank Kenya Assets and Liabilities
The additional buffer would range from 0.5 percent to 2.5 percent of a bank’s risk-weighted assets, depending on its level of systemic importance.
CBK would assess banks using five criteria to determine which qualify as D-SIBs. These include their size, interconnectedness with other financial institutions, substitutability of their services, complexity of operations and importance to the domestic economy.
Size would account for the largest share of the assessment at 40 percent, followed by interconnectedness at 30 percent. Substitutability would carry 15 percent, economic importance 10 percent, and complexity 5 percent.
The proposed rules also require larger banks to hold sufficient capital to support smaller lenders as they work toward meeting the KSh10 billion minimum core capital requirement.
Follow our WhatsApp Channel and X Account for real-time news updates.