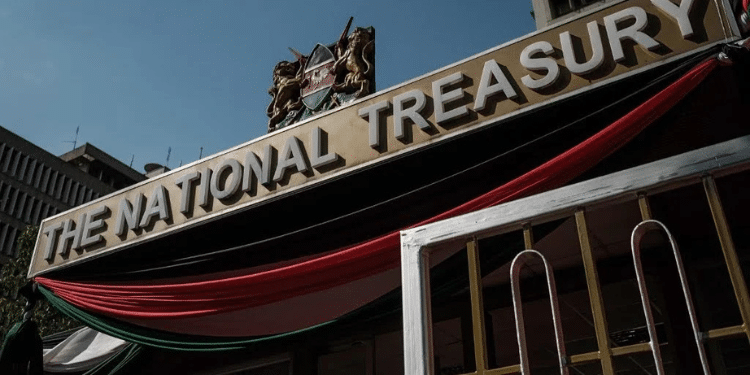
The National Treasury and the Central Bank of Kenya (CBK) have launched public participation on a proposed law that could significantly reshape Kenya’s digital payments landscape, including mobile money, banking transactions, and fintech services.
In a notice on September 22, the two institutions said they have developed the Draft National Payment System Policy and the National Payment System Bill, 2026, which seeks to modernize the country’s payments framework and replace the existing National Payment System Act.
According to the notice, the proposed policy aims to establish a payment system that is safe, secure, efficient, affordable, accessible, and inclusive.
It is also expected to support interoperability, innovation, financial inclusion, and Kenya’s integration into regional and global payment systems.
How Digital Payments Could Change
The Bill requires payment service providers and payment system operators to use systems that can work seamlessly with those of other providers.
It also empowers CBK to direct firms to enter into interoperability arrangements where necessary.
The reforms are intended to address fragmentation that Treasury says continues to affect Kenya’s payment landscape despite growth in mobile money and digital financial services.
According to the draft policy, limited interoperability across banks, mobile money providers, payment service providers, and government platforms has contributed to inefficiencies and higher transaction costs.
Also Read: PSC Announces 851 Govt Jobs Across Ministries: How to Apply
Another major proposal is the introduction of “open finance,” which would allow third parties to access customer data held by payment providers, subject to customer consent.
The Bill requires payment providers and payment system operators to use systems that can securely share customer information to develop new products and services.
The proposed framework also seeks to improve cross-border payments by supporting greater integration with regional and global payment systems.
Treasury says the current framework does not adequately address regional payment connectivity despite Kenya’s growing trade links within the East African Community, COMESA and the African Continental Free Trade Area.
Treasury argues that emerging technologies and changing consumer needs require a modern regulatory framework that supports innovation while maintaining financial stability.
The policy notes that existing laws have not kept pace with developments such as open finance, instant payments, virtual assets, cross-border transactions, and new digital payment models.
Interoperability and Innovation
The draft policy outlines plans to develop a national instant payment switch to enable fast, secure, and affordable transactions across the payment ecosystem.
The government also plans to develop digital public infrastructure and strengthen payment market infrastructure to support real-time transactions.
Also Read: Dollar Fails to Shake Kenya Shilling Despite Rising US Interest Rates
The Bill introduces specific licensing categories covering payment initiation service providers, account information service providers, merchant acquirers, electronic wallet providers, electronic money issuers, payment gateways, and payment messaging operators.
It also brings virtual asset service providers offering payment services under the regulatory framework.
The Bill further requires electronic money issuers and digital wallet providers to hold customer funds in trust accounts and maintain balances equal to what they owe customers.
Customer funds held in those trust accounts would be protected from attachment or use in settling the provider’s debts in the event of insolvency.
More CBK Powers
Under the proposed law, CBK would gain wider supervisory powers.
The regulator would have authority to inspect payment firms, issue directives, intervene in management, appoint statutory managers, and impose administrative penalties where providers fail to comply with the law or pose risks to customers and the wider financial system.
The proposed law further requires firms to report major incidents such as cyberattacks, data breaches, prolonged service outages, loss of customer funds, and significant ownership changes.
Treasury says stronger oversight is necessary as Kenya’s payment ecosystem becomes increasingly interconnected and dependent on digital infrastructure.
The government has invited members of the public to submit views on both the draft policy and the Bill before October 9, 2026, after which the proposals will be reviewed before being taken through the legislative process.
Follow our WhatsApp Channel and X Account for real-time news updates.