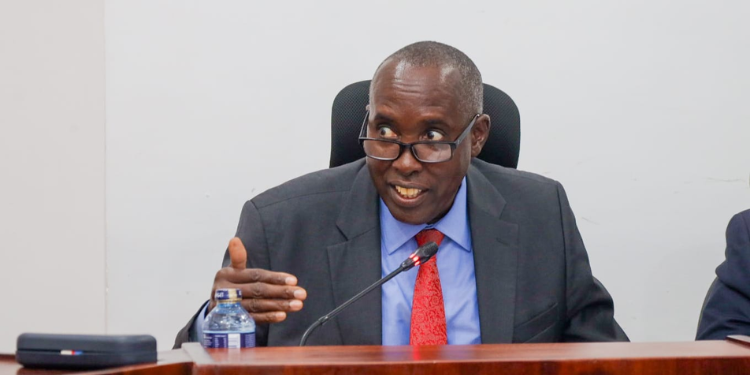


The Kenya Revenue Authority (KRA) has clarified the issue of missing August 2026 invoices from taxpayers’ returns after a taxpayer raised the concern.
According to the tax authority, it is uploading the missing invoices to the system in batches, which is why they appear missing on taxpayers’ returns.
“What’s up with missing invoices and wrong sales in the auto-population for VAT? Advice on the way forward,” Samwel Waweru inquired about the missing invoices on September 12.
In response on September 14, the authority advised affected taxpayers to check their CSVs again during the course of the week as the August invoices continue to be uploaded.
Taxpayers whose invoices remain missing have also been asked to send the relevant invoice numbers to KRA’s TIMS support team through [email protected].
Also Read: Importers and Clearing Agents Face 12-Hour KRA System Shutdown
Why Invoices May Be Missing
KRA’s VAT auto-populated return draws information from iTax, TIMS, eTIMS and customs systems.
The authority says it updates the information through incremental batch processing, so it may appear after an earlier version of the CSV has been downloaded.
In addition, the authority argued that the auto-populated return does not relieve the taxpayer of the responsibility to declare all sales for the relevant tax period.
“Note that the August 2026 invoices are uploaded to the VAT auto-populated CSVs in batches. Sales in the VAT return are prepopulated based on the invoice date and not the transmission date. Hence, a taxpayer needs to declare all their total sales in the VAT return, whether transmitted or not, by the date of filing the return,” KRA states.
For taxpayers with missing sales issued outside TIMS/eTIMS or not transmitted by the time of filing, the authority said the taxpayer can increase the sales value in the return to account for them.
Also Read: Ruto Signs Law Giving KRA New Role in Air Passenger Charges
KRA Directives to Taxpayers
To avoid having missing VAT invoices, the authority advises taxpayers to verify invoices before submitting returns.
Additionally, the taxpayer must cross-check the VAT auto-populated CSV against the sales ledger and eTIMS record.
To correct a wrongly captured buyer PIN, a taxpayer should issue a credit note to reverse the erroneous sale and then reissue the invoice with the correct PIN.
However, where the correct PIN was captured but was not transmitted, the seller should work with the TIMS supplier to resolve the configuration issue and transmit the correct information.
At the same time, erroneous invoices can be reversed through a credit note in instances of duplicated sales invoices resulting from configuration problems between a trader’s invoicing system and TIMS.
KRA also allows taxpayers to remove or disallow erroneous purchases, including prohibited input tax, appearing in the purchase CSV.
Follow our WhatsApp Channel and X Account for real-time news updates.