Parliament has directed the Central Bank of Kenya (CBK) to suspend the rollout of proposed regulations governing non-deposit-taking credit providers, citing concerns about excessive administrative powers, unlawful penalties, and weak legal drafting.
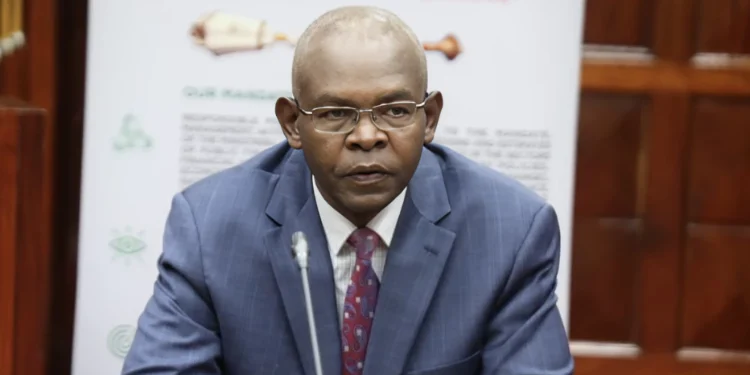
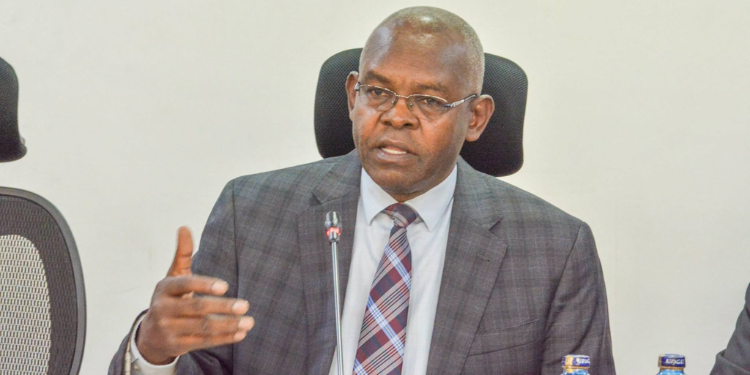
The National Assembly’s Delegated Legislation Committee, chaired by Ainabkoi MP Samuel Chepkonga on November 12, questioned whether the proposed regulations complied with the Statutory Instruments Act, warning that some provisions could expose businesses to arbitrary enforcement and undermine consumer protection.
Chepkonga said the proposed provisions gave the regulator excessive discretion and could leave businesses uncertain about their legal obligations.
“What we do not allow you is to have open-ended discretion. Kenyans must be given notice and know what the law requires of them. You cannot introduce vague provisions that deny people an opportunity for public participation,” Chepkonga said.
“The Statutory Instruments Act provides for a maximum which these regulations exceed. Already, that is inconsistent. It makes these regulations themselves void.”
MPs Reject CBK’s Proposed Regulations for Credit Providers
The proposed regulations seek to expand CBK’s oversight beyond digital lenders to cover buy-now-pay-later platforms, asset financiers, peer-to-peer lenders and other non-deposit-taking credit providers.
The reforms aim to address high borrowing costs, predatory debt collection practices, and the misuse of customers’ personal information.
CBK officials told the Committee that the regulator had received more than 900 licence applications since the digital credit framework was introduced in 2022. By September 2026, 281 providers had been licensed, with loans valued at approximately Ksh165.1 billion.
However, lawmakers questioned provisions that would allow CBK to demand additional documents or prescribe other functions without clearly defining the scope of its powers.
Bonchari MP Charles Onchoke also faulted the draft regulations for using complex legal language, warning that ordinary Kenyans could struggle to understand their obligations under the proposed rules. He called on CBK to simplify the wording so the regulations are accessible to non-lawyers.
The Committee further objected to Clause 86, which proposes financial penalties of up to Ksh2 million, arguing that the amount exceeds the maximum limit allowed under the Statutory Instruments Act.
Also Read: How AI Could Revolutionise the Way CBK Monitors Kenya’s Economy
What the Rules Say
The proposed regulations require businesses seeking to offer non-deposit-taking credit services in Kenya to obtain a licence from the Central Bank of Kenya (CBK) before commencing operations, unless they are already regulated under another written law.
Under the rules, companies seeking a licence must have an initial capital of at least Ksh20 million and submit an application detailing their ownership, source of funds, business operations and lending products.
Applicants must also provide information on their interest rates, loan sizes, credit policies, consumer protection measures, data protection systems and procedures for handling customer complaints.
The regulations further require companies to submit audited financial statements, where applicable, along with details of their directors, shareholders, and senior managers. The officials must provide certificates of good conduct, tax compliance certificates and credit reference bureau reports.
Also Read: CBK Summons Two Banks Struggling to Raise Capital
CBK would assess applications based on the completeness of submitted documents, the suitability of proposed directors and managers, the source of investment funds, and the public interest served by licensing the business.
The regulator would have up to 60 days to issue a licence after an application is submitted. Licences would remain valid unless suspended or revoked, while licensed providers would be required to pay annual fees by December 31 each year.
Companies that fail to pay the annual fees on time would be required to pay double the amount if they settle within three months after the deadline. Failure to meet this extended deadline could result in the revocation of their licences.
The rules also give CBK the power to discontinue processing licence applications if applicants fail to provide requested additional information for three months. Before doing so, the regulator would issue a 14-day notice allowing the applicant to explain why the application should not be discontinued.
Applicants whose applications are discontinued would be allowed to submit fresh applications under terms set by CBK.
Follow our WhatsApp Channel and X Account for real-time news updates and subscribe to our YouTube Channel for in-depth interviews.